Insurance
What Is MetLife Health Savings Plan (MHSP) and How Does It Work?
2026 ,27 Sep
Insurance
What Is MetLife Health Savings Plan (MHSP) and How Does It Work?
Healthcare expenses may arise unexpectedly, while future medical needs can require long-term financial preparation. Alongside preparing for healthcare expenses, individuals may also need to consider savings, life insurance protection, hospitalization-related support, critical illness coverage and accident-related medical costs.
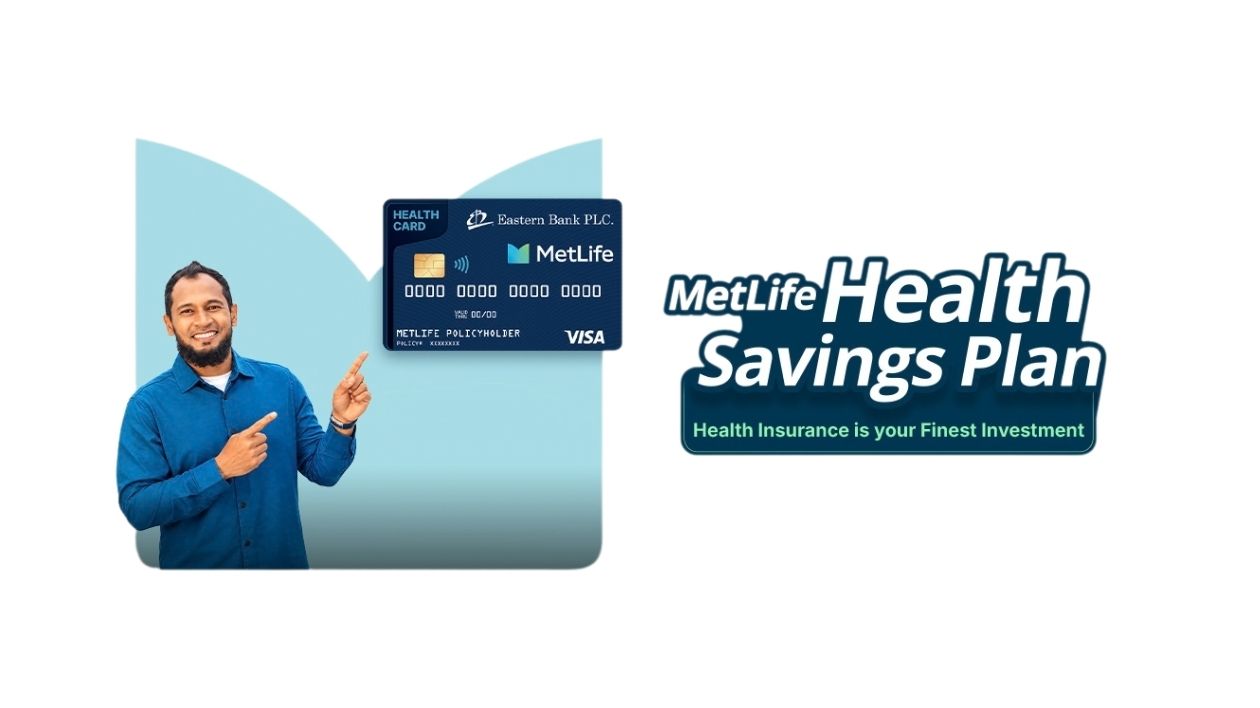
MetLife Health Savings Plan (MHSP) is a life insurance policy designed to help policyholders build savings while accessing health-related features and benefits. MHSP combines life insurance protection, a Basic Account Value, the MetLife Health Wallet, a co-branded Health Card and the option to add selected health and accident riders according to individual needs.
How Does MetLife Health Savings Plan Work?
Under MetLife Health Savings Plan, policyholders pay premiums and build a Basic Account Value according to the applicable policy terms and conditions.
Policyholders can also deposit additional funds into the MetLife Health Wallet to prepare for future health-related expenses. The available Health Wallet balance and an eligible portion of the Basic Account Value can be accessed through the MetLife Health Card for health-related payments, subject to the applicable policy and card rules.
MHSP also provides maturity and death benefits. Policyholders may customize their protection by adding selected hospitalization, critical illness and accident-related riders when purchasing the policy.
What Are the Base Benefits of/content/metlife/bd/homepage/solutions/health-and-protection/mhsp?
The MHSP base policy provides maturity, death and additional accidental benefits.
Maturity Benefit
The MHSP maturity benefit consists of:
The applicable maturity benefit remains subject to the MHSP policy terms and conditions.
Death Benefit
The MHSP death benefit consists of:
All applicable death benefits remain subject to the MHSP policy terms and conditions.
Additional Accidental Coverage
MHSP provides additional accidental coverage of up to five times the Face Amount.
The applicable amount and availability of additional accidental coverage depend on the relevant policy terms, limits and conditions.
This base benefit is different from Accidental Medical Reimbursement, which is an optional rider for eligible medical expenses arising from an accident.
How Can MHSP Protection Be Customized?
MHSP policyholders can customize their protection by adding selected health and accident riders when purchasing the policy.
These riders require additional premiums and are not automatically included in the MHSP base policy.
In-Hospital Daily Income
The In-Hospital Daily Income rider provides coverage of up to BDT 20,000 per day during hospitalization.
The applicable daily benefit remains subject to the rider’s eligibility requirements, limits and terms and conditions.
Critical Illness: Health Essential
The Critical Illness or Health Essential rider provides coverage against eight critical illnesses.
Coverage applies only to the critical illnesses and conditions defined in the approved rider documents.
Critical Care: Health Extensive
The Critical Care or Health Extensive rider provides broader coverage against 25 critical illnesses.
Health Extensive covers more specified critical illnesses than Health Essential. The selection of a rider should depend on the policyholder’s needs, premium affordability, eligibility and the applicable rider terms and conditions.
Accidental Medical Reimbursement
The Accidental Medical Reimbursement rider provides reimbursement of eligible medical expenses arising from an accident, up to the specified rider limit.
The qualifying expenses, required documents, exclusions, reimbursement limits and other provisions remain subject to the applicable rider terms and conditions.
What Is the MetLife Health Wallet?
The MetLife Health Wallet is an exclusive MHSP benefit that allows policyholders to make optional Top-Up deposits for future health-related expenses.
Policyholders can add funds to the MetLife Health Wallet within the allowable limits. The available Wallet balance can then be used for eligible health-related payments through the MetLife Health Card.
Top-Up deposits may be made through:
MHSP policyholders can make Top-Up deposits and transactions while the policy remains active. Top-Up deposits can be made only when regular policy premiums are up to date and must comply with the applicable minimum and maximum Top-Up limits.
The applicable crediting interest rate on the MetLife Health Wallet fund may help the accumulated balance grow over time, subject to the policy terms and conditions. The crediting interest rate should not be interpreted as an investment return, yield, profit rate, return on investment or guarantee of financial performance.
The MetLife Health Wallet is an MHSP policy benefit. It should not be interpreted as a conventional savings account, bank account or investment account.
What Is the MetLife Health Card?
The MetLife Health Card is a co-branded prepaid card offered by MetLife in partnership with Eastern Bank PLC to provide MHSP policyholders access to eligible funds for health-related payments.
Every active MHSP policyholder is eligible to receive a Health Card. The card can be used for eligible cashless payments at:
The cashless payments will be in BDT, and within the approved merchant network in Bangladesh.
The available Health Card balance may include:
Cash withdrawal and fund transfer are not permitted through the MetLife Health Card.
Cashless payment means using the available Health Card balance to make an eligible health-related payment. It does not mean that healthcare services are free, automatically covered or available without applicable limits.
The MetLife Health Card is a co-branded prepaid card. It should not be interpreted as a conventional bank account, debit card, credit card or unrestricted general-purpose payment card.
How Can the Basic Account Value Be Used for Health-Related Expenses?
Starting from the second MHSP policy year, a policyholder may use an eligible portion of the Basic Account Value for health-related expenses through the MetLife Health Card.
The applicable Basic Account Value portion is determined by the relevant policy year:
Up to 100% of the principal balance in the MetLife Health Wallet may be available through the Health Card, subject to the applicable policy rules.
The usable Health Card limit is determined using:
Principal balance in the MetLife Health Wallet + eligible portion of the Basic Account Value
All available amounts, limits and eligible transactions remain subject to the applicable MHSP terms and conditions.
What MHSP Membership Options Are Available?
MetLife Health Savings Plan provides three membership options based on the applicable monthly premium: Premium Plus, Premium and Standard.
For premium payment modes other than monthly, the applicable premium amount is determined as a multiple of the monthly premium.
The maximum amount that can be used in a transaction also depends on the policyholder’s available balance. There is no limit on the number of daily transactions as long as sufficient balance remains available under the policy.
The applicable offers and benefits associated with each membership tier remain subject to the approved MHSP materials and relevant conditions.
How Does One by MetLife Support MHSP Policyholders?
MHSP is integrated with the One by MetLife app, allowing
policyholders to access policy, Health Wallet and Health Card information.
Through One by MetLife, policyholders can access:
Policyholders may also use the app for selected Health Card requests, including renewal and replacement, subject to the applicable conditions.
How Can Policyholders Add Funds to the MetLife Health Wallet?
Policyholders can add funds through:
Top-Up deposits are accepted only when the MHSP policy remains active and regular premium payments are up to date.
There is no minimum Top-Up amount required until further notice. However, Top-Up deposits remain subject to MetLife’s applicable minimum and maximum limits and policy rules.
Top-Up amounts are not included in the Premium Certificate. The Premium Certificate reflects only the Policy Premium Amount.
What Happens If an MHSP Premium Remains Unpaid?
If an MHSP premium remains unpaid for 31 days from the due date, the due premium will be automatically deducted from the MetLife Health Wallet, subject to sufficient available Wallet balance.
A new Top-Up deposit will be accepted only after the regular policy premium is brought up to date. However, any existing MetLife Health Wallet balance may still be used for eligible health-related expenses, subject to the applicable policy rules.
What Happens to Unused MetLife Health Wallet Funds?
Any unused MetLife Health Wallet balance will be refunded to the policyholder if the MHSP policy:
Health Card transactions will be disabled automatically when the policy matures, terminates, lapses or is surrendered.
The refund and closure process remains subject to the applicable MHSP and MetLife Health Wallet rules.
What Should Customers Review Before Choosing MHSP?
Before choosing MetLife Health Savings Plan, customers should review:
The suitability of MHSP depends on the customer’s savings objectives, life insurance needs, healthcare-related financial priorities, premium affordability and individual circumstances.
Key Takeaways
________________________________________________________________________________________
Disclaimer: The MetLife Health Card is issued, maintained, and operated exclusively by the partner bank pursuant to its own systems, processes, and applicable terms and conditions. MetLifeʼs role is limited to facilitating access to the Health Card as a policy benefit called the “MetLife Health Walletˮ which is integrated with the MetLife Health Savings Plan. MetLife does not own, control, or manage the bankʼs card infrastructure, transaction processing systems, payment networks, merchant acquisition, dispute resolution mechanisms, or customer service operations. Accordingly, MetLife shall not be liable for any delay, failure, interruption, error, omission, unauthorized transaction, declined transaction, dispute, reversal issue, system unavailability, or service deficiency arising out of or in connection with the bankʼs issuance, activation, PIN management, transaction processing, settlement, blocking, reissuance, or other card-related services.
All queries, complaints, and disputes relating to the Health Card or card transactions must be raised directly with the issuing bank and shall be governed by the bankʼs applicable policies, timelines, and regulatory obligations
Financial Disclaimer: The information provided is for general informational purposes only and should not be considered financial, investment or insurance advice. Policy features, premiums, Face Amount, benefits, bonuses, coverage limits, optional riders, outstanding debts and other terms may vary. Please review the approved policy literature and consult a qualified financial advisor before making any financial decision.
Discover investment and savings plans in Bangladesh. Learn how to build wealth, manage risk, and secure your financial future with the right investment strategy.
Learn how to choose the right investment in Bangladesh by understanding your financial goals, risk tolerance, and investment timeline for long-term growth.
Learn what portfolio investment is, its benefits, risks, and types. Discover how to build a diversified investment portfolio and achieve your financial goals.
Learn the 7 early signs of kidney disease you shouldn't ignore. Discover common symptoms, warning signals, and when to seek medical advice for better kidney health.
Learn the five warning signs parents should never ignore during a disease outbreak and when to seek medical advice for their children.
Looking for the right insurance?
We will get back to you soon with the help you need.